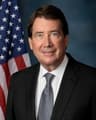
Bill Hagerty (R-TN)
Main Street Depositor Protection Act
A Republican bill with 1 Democratic cosponsor · See the cosponsor
Last activity — Committee on Banking, Housing, and Urban Affairs. Hearings held.
In committee
Introduced and handed to a committee in the chamber it started in.
The committee holds it, and most bills are never heard from again. A hearing or a committee vote would be news; silence is the usual outcome, and it kills the bill without anyone voting against it.
Its path through Congress
- Introduced
- In Committee
What this bill would do
The "Main Street Depositor Protection Act" aims to amend the Federal Deposit Insurance Act and the Federal Credit Union Act. It provides for increased deposit insurance specifically for noninterest-bearing transaction accounts. Under this bill, the Corporation and the Board will insure these accounts up to an aggregate amount of $10,000,000. This coverage applies to both insured depository institutions and insured credit unions. The bill includes a transition period where insurance coverage is gradually increased over 10 years.
Yes· 3 of 8
- Scored +4
Would business owners be better off under this?
Business owners can secure much higher amounts of operating cash in transaction accounts with federal insurance protection.
- Scored +3
Would households on low incomes be better off under this?
Increased deposit insurance coverage provides greater security for liquid funds held in transaction accounts.
- Scored +3
Would middle-income households be better off under this?
The expansion of insurance for noninterest-bearing accounts provides increased protection for personal funds.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Increased Insurance for Specific Accounts: The bill allows the Corporation to insure the net amount in noninterest-bearing transaction accounts up to $10,000,000 (Section 2(a)(1)(ii)(I)). This could provide higher levels of protection for individuals maintaining these types of accounts.
-
Protection for Credit Union Members: The Board will insure the net amount in noninterest-bearing transaction accounts for members or eligible persons at insured credit unions up to $10,000,000 (Section 2(b)(1)(A)(ii)(I)).
-
Relief for Smaller Institutions: During the transition period, depository institutions with total assets of $10,000,000,000 or less will not be required to pay certain special assessments or any increases in assessments intended to offset the impact on the reserve ratio (Section 2(a)(3)).
Potential Negative Impacts for People
-
Exclusion of Certain Banks: The insurance coverage does not apply to any insured depository institution that is a subsidiary of a bank holding company identified as a global systemically important BHC (Section 2(a)(1)(ii)(III)(bb)(AA)).
-
Exclusion of Foreign Bank Branches: The Corporation is prohibited from insuring amounts maintained at any insured branch of a foreign bank (Section 2(a)(1)(ii)(III)(bb)(BB)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Tap or hover a score for the reason it gave.
- Demographic And Interest Groups
- Would business owners be better off under this? — Business owners can secure much higher amounts of operating cash in transaction accounts with federal insurance protection. Would households on low incomes be better off under this? — Increased deposit insurance coverage provides greater security for liquid funds held in transaction accounts. Would middle-income households be better off under this? — The expansion of insurance for noninterest-bearing accounts provides increased protection for personal funds. Would high-income households be better off under this? — The bill increases insurance limits for high-value transaction accounts up to $10,000,000. Would people in rural areas be better off under this? — The bill provides broad insurance protections that apply to all eligible depositors regardless of location. Would people in cities be better off under this? — The bill provides broad insurance protections that apply to all eligible depositors regardless of location.
- Economy And Finance
- Does this make it easier to run a small business? — Small depository institutions with assets under $10 billion are spared from certain special assessments and potential assessment increases. Does this make the government pay for what it commits to? — The bill provides exemptions from certain special assessments and assessment increases for smaller depository institutions during a transition period.
- 2/5/2026
- Committee on Banking, Housing, and Urban Affairs. Hearings held.
- 10/9/2025
- Read twice and referred to the Committee on Banking, Housing, and Urban Affairs.
- 1 Cosponsor added.
- Introduced in Senate
2 bills Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
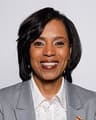 Angela Alsobrooks
Democrat · Maryland